CFO Message
Steady Profit Growth and Revenue Base Enhancement
Despite the impact on logistics caused by the high tensions in the Middle East at the end of the fiscal year ended March 31, 2026, and the temporary losses that we anticipated, we were able to reach a new record-high profit, which I see as a tremendous success.
Our success isn’t being driven by a single division, but instead by The environment surrounding us has changed dramatically in recent years. This includes increasing geopolitical risks and the rebuilding of supply chains. Last fiscal year, as well, there were concerns about the impact of changing U.S. trade policies, but we managed to minimize their impact on us. In fact, by dealing with the new issues that arose, we further expanded our role from customers.
On the financial front, we stayed conscious of our balance sheet as we carried out our operations. While logistics disruptions resulted in shipping delays and an increase in inventories due to strategic stock expansion toward the end of the fiscal year ended March 31, 2026, we maintained a high operating cash flow of roughly 500.0 billion yen. Cash-generating power is an important metric that indicates the actual strength of a business. Cash is also an important resource that supports both growth investment and shareholder returns.
This significantly reduced our strategic cross-shareholdings, which I believe served as a great stride toward producing a leaner balance sheet and improving capital efficiency.
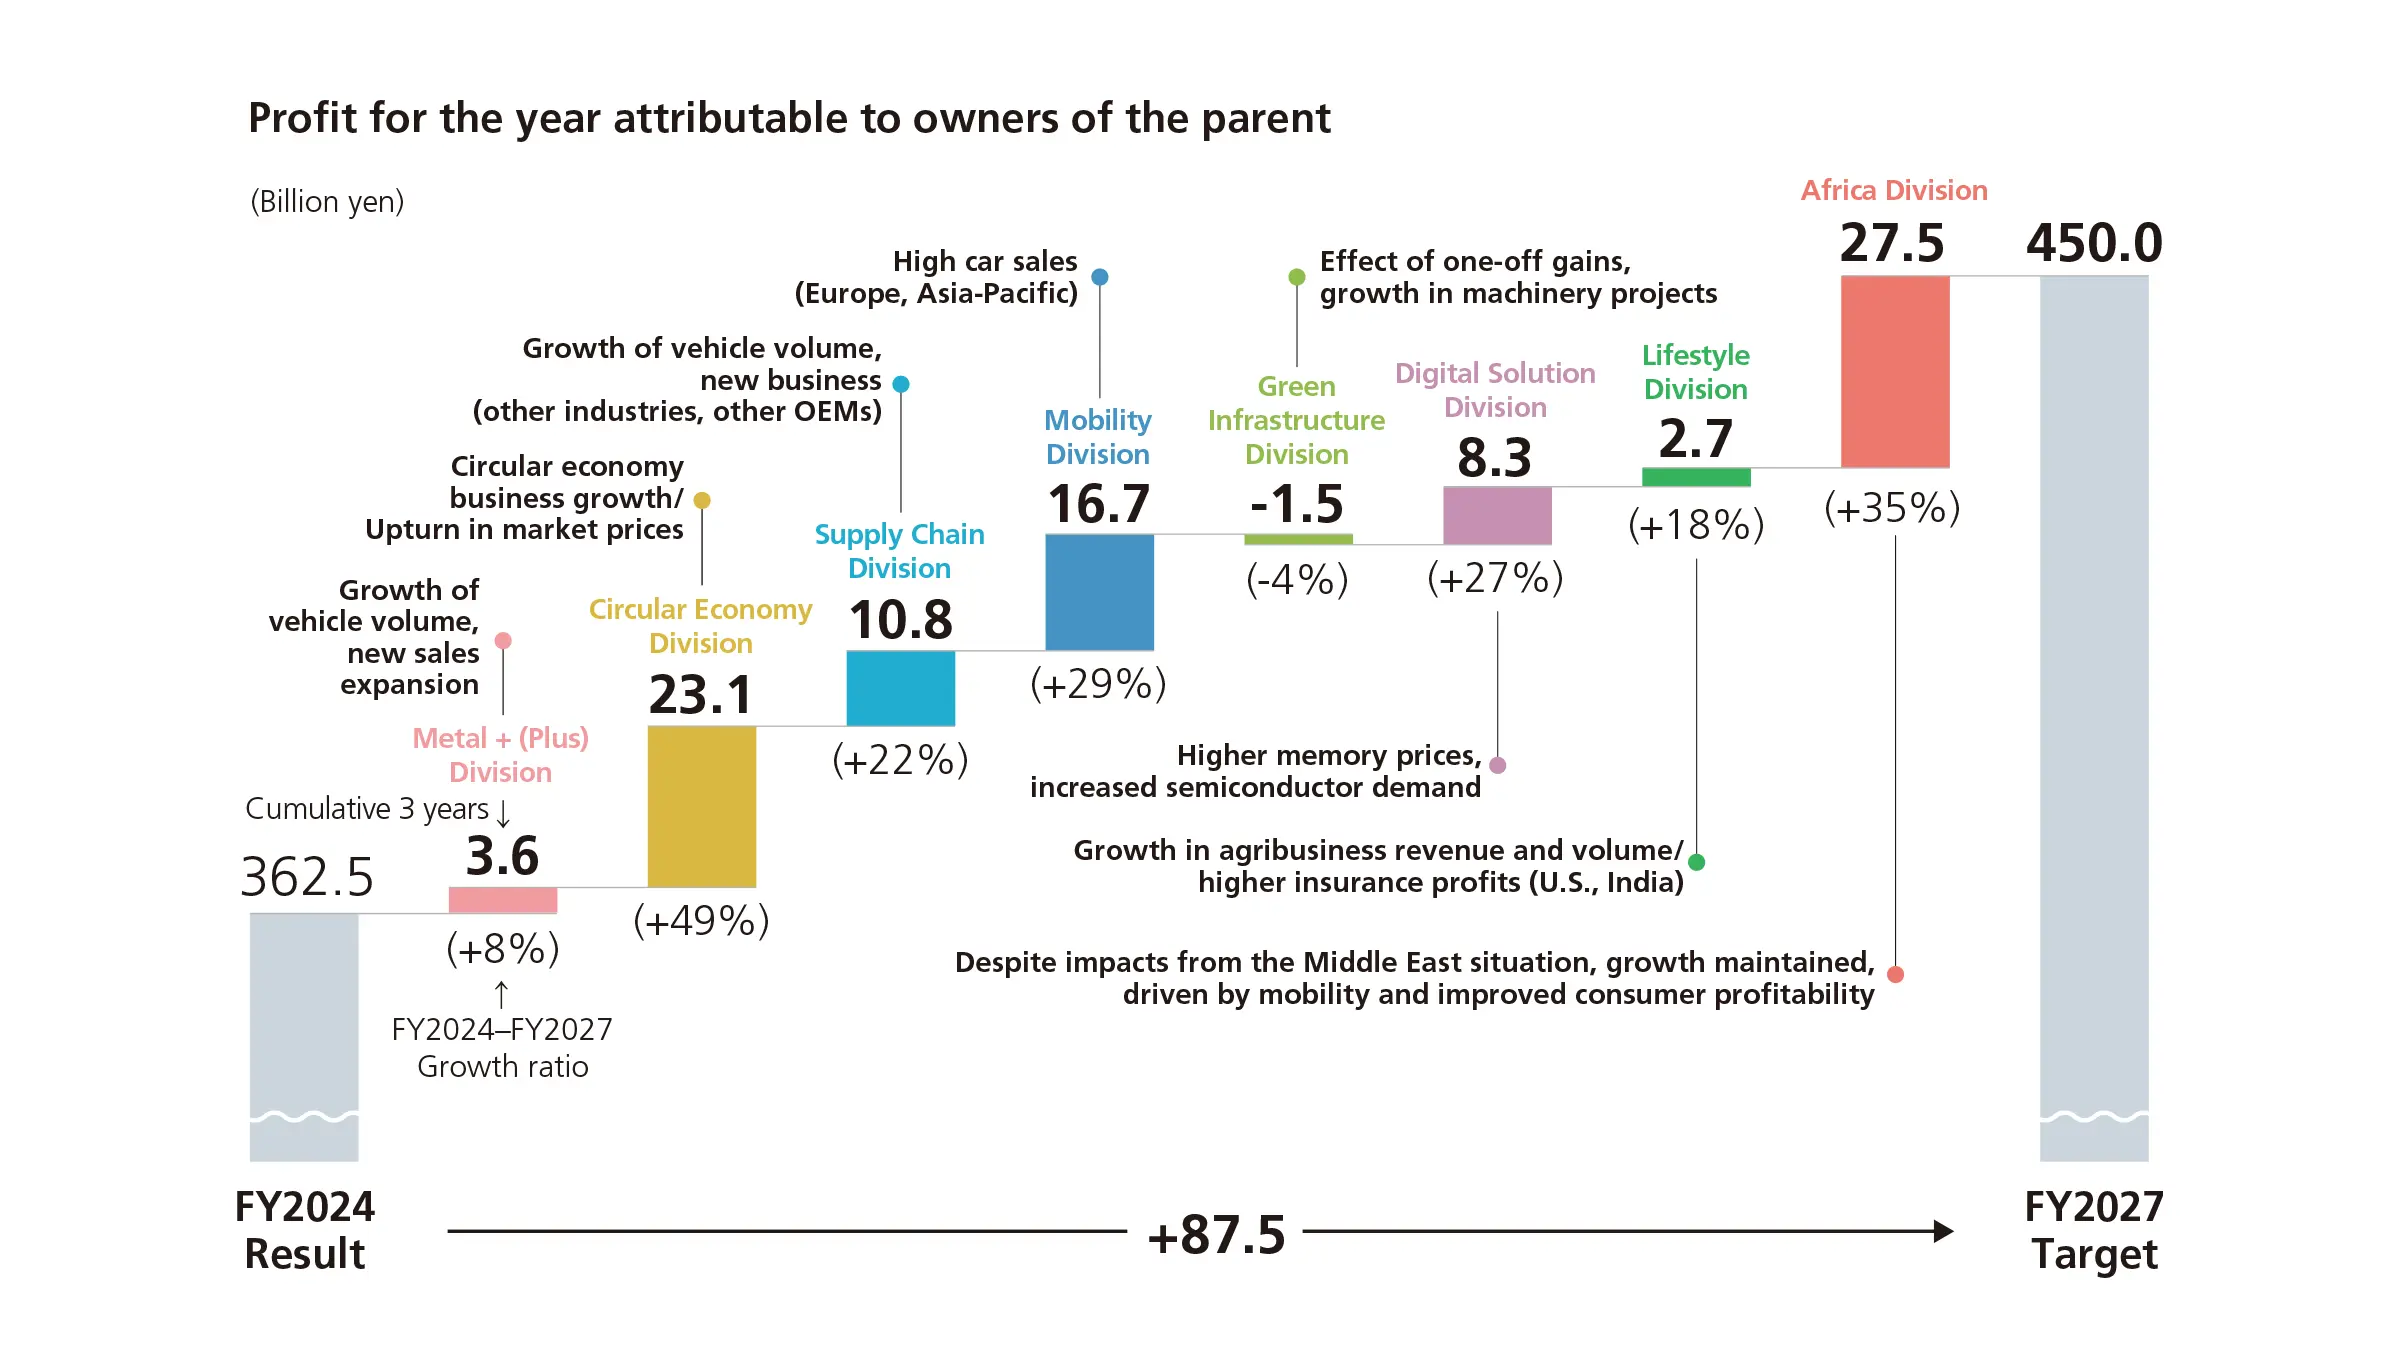
Reaching 450.0 Billion Yen in Profit for the Year through Organic Growth
At the end of April 2025, we announced our new Medium-Term Management Plan (MTP) for the fiscal years ending March 31, 2026, through March 31, 2028. We also switched from a rolling basis to a fixed period basis. Under this plan, we will wholeheartedly commit ourselves to achieving our targets, even in the face of the rising uncertainty in the external environment.
In the second year of the MTP, the fiscal year ending March 31, 2027, we initially took a prudent approach, with a conservative plan that reflected geopolitical risks and supply chain changes, and set a target profit for the year of 400.0 billion yen. However, based on our first-quarter results and the current business environment, we revised this target upward to 430.0 billion yen.
In our existing businesses, we will not rely on new large-scale investment but instead improve profitability by increasing the added value of our services and functions.
This profit growth and cash-generating power are supported by the customer base that we have built through the years. We don’t just move goods and connect logistics; we combine various functions to create value by solving the problems faced by our customers. This customer base, firmly rooted in the field, is one of Toyota Tsusho’s strengths and the source of our ability to adapt to changes in the environment.
President & CEO Imai’s concept of the organization as a living organism-like supply chain is a clear encapsulation of these features. Instead of relying on a single route, we identify which options are best given current conditions, and we combine multiple functions as we create value. This flexibility and autonomy in our organization support our sustainable creation of new value in the face of a changing environment.
The Next Stage of Growth that Will Be Achieved Through Investment in Uniquely Competitive Areas and Business Portfolio Reforms
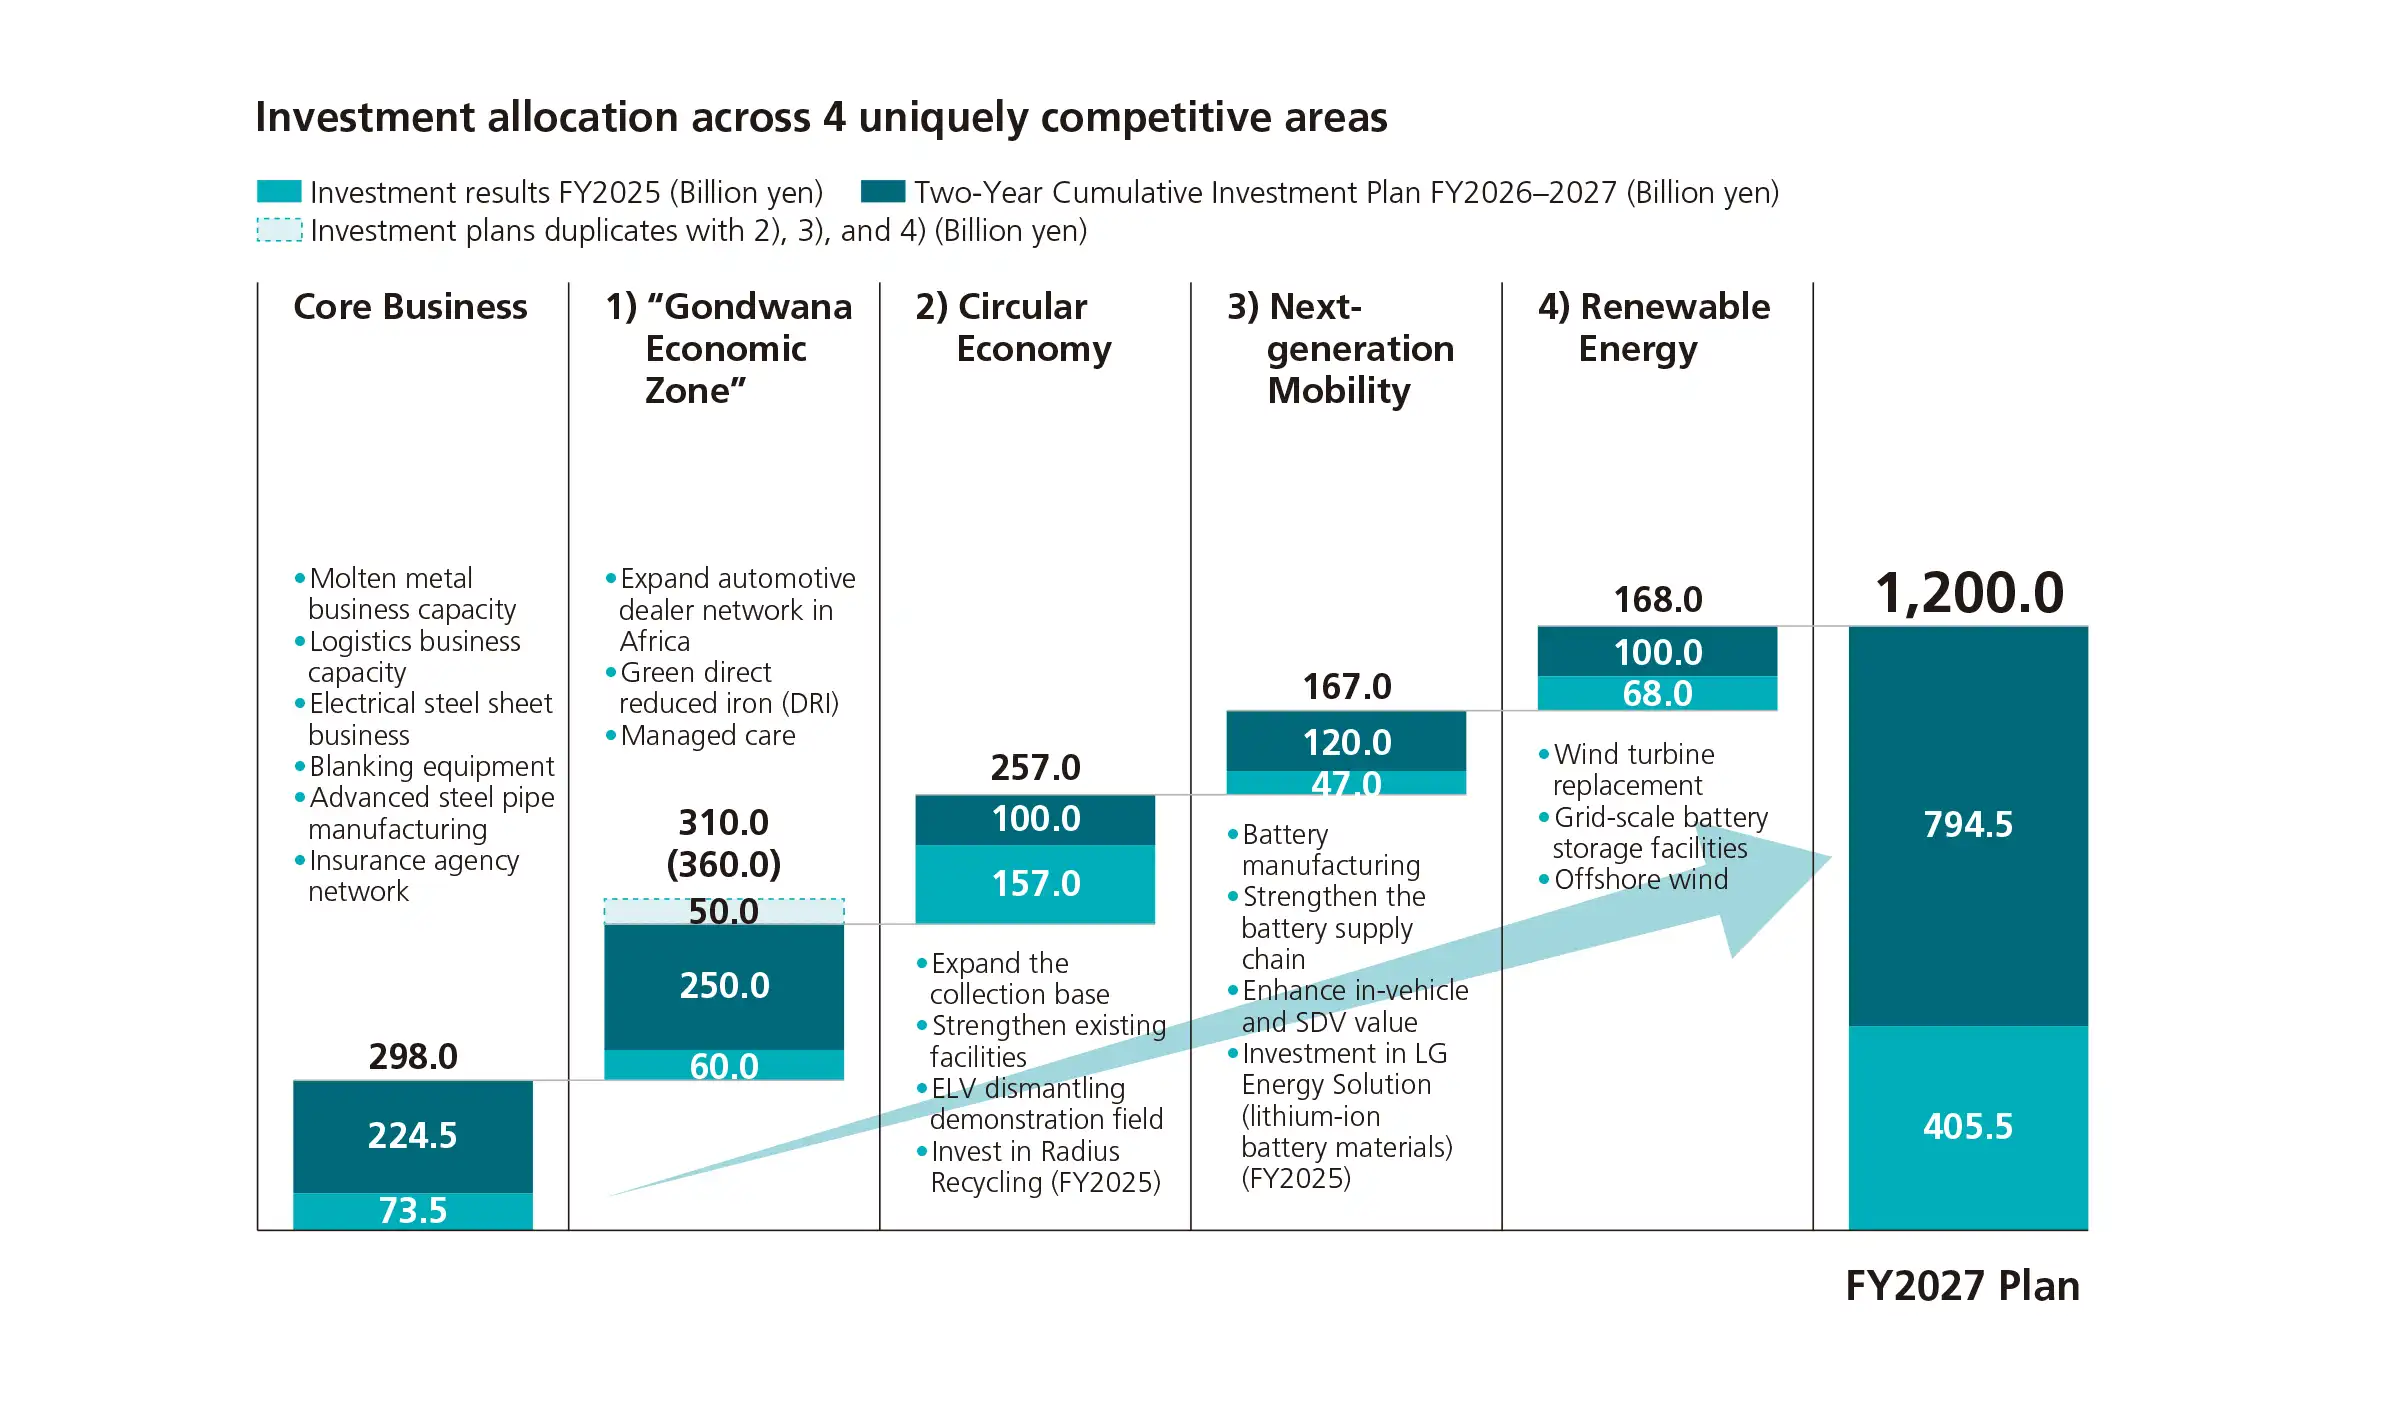
Under the MTP, We believe the Africa-centered “Gondwana Economic Zone” has the greatest room for growth. We already have a business foundation throughout Africa, and we have grown our sales revenue to roughly 1.9 trillion yen and our profit for the year to over 94.0 billion yen while expanding from automobile sales to the healthcare, consumer, and green infrastructure business domains. Led by the “Gondwana Economic Zone” concept, under the MTP we will connect Africa, India, and Brazil, creating new distribution channels. In India, in addition to manufacturing focused on automobiles, we are also expanding in the healthcare domain. In Brazil, we are working to strengthen our food value chain, which is based in the ports in the north of the country. The circular economy is another domain with a great deal of potential. From an early stage, we have allocated business resources to the resource recycling field. In recent years, a growing amount of attention has been turned to the recycling of batteries and other resources. We believe that this field will continue to experience major growth, and we can demonstrate our value as a pioneer. In the next-gereration mobility field, we combine multiple products and technologies, using the foundation of the knowledge we have accrued through our automotive semiconductor business to provide solutions based on the needs of individual customers. One of our strengths is our ability to provide value, including quality management, stock management, and design functions. As the use of AI and software grows, we believe this will present us with major growth opportunities.
In the renewable energy field, we are placing great importance on profitability. In Africa, especially, we have many projects for which we anticipate a high return on investment, so we consider this region a promising investment region. Within Japan, as well, we are working to improve profitability by raising the efficiency of existing facilities and coordinating with storage battery facilities and data centers.
Investing in uniquely competitive areas isn’t all that we’re doing, though. We will also continuously review and revise our business portfolio. For example, we have pulled out of the oil and coal business and the thermal power generation business, shifting our business resources to growth fields. We are reviewing businesses with low levels of profitability and are continuing to accelerate our corporate metabolism by also reviewing the standards we use to make decisions regarding pulling out of or reorganizing these businesses. We will keep on reallocating our business resources to more profitable fields with greater growth potential.
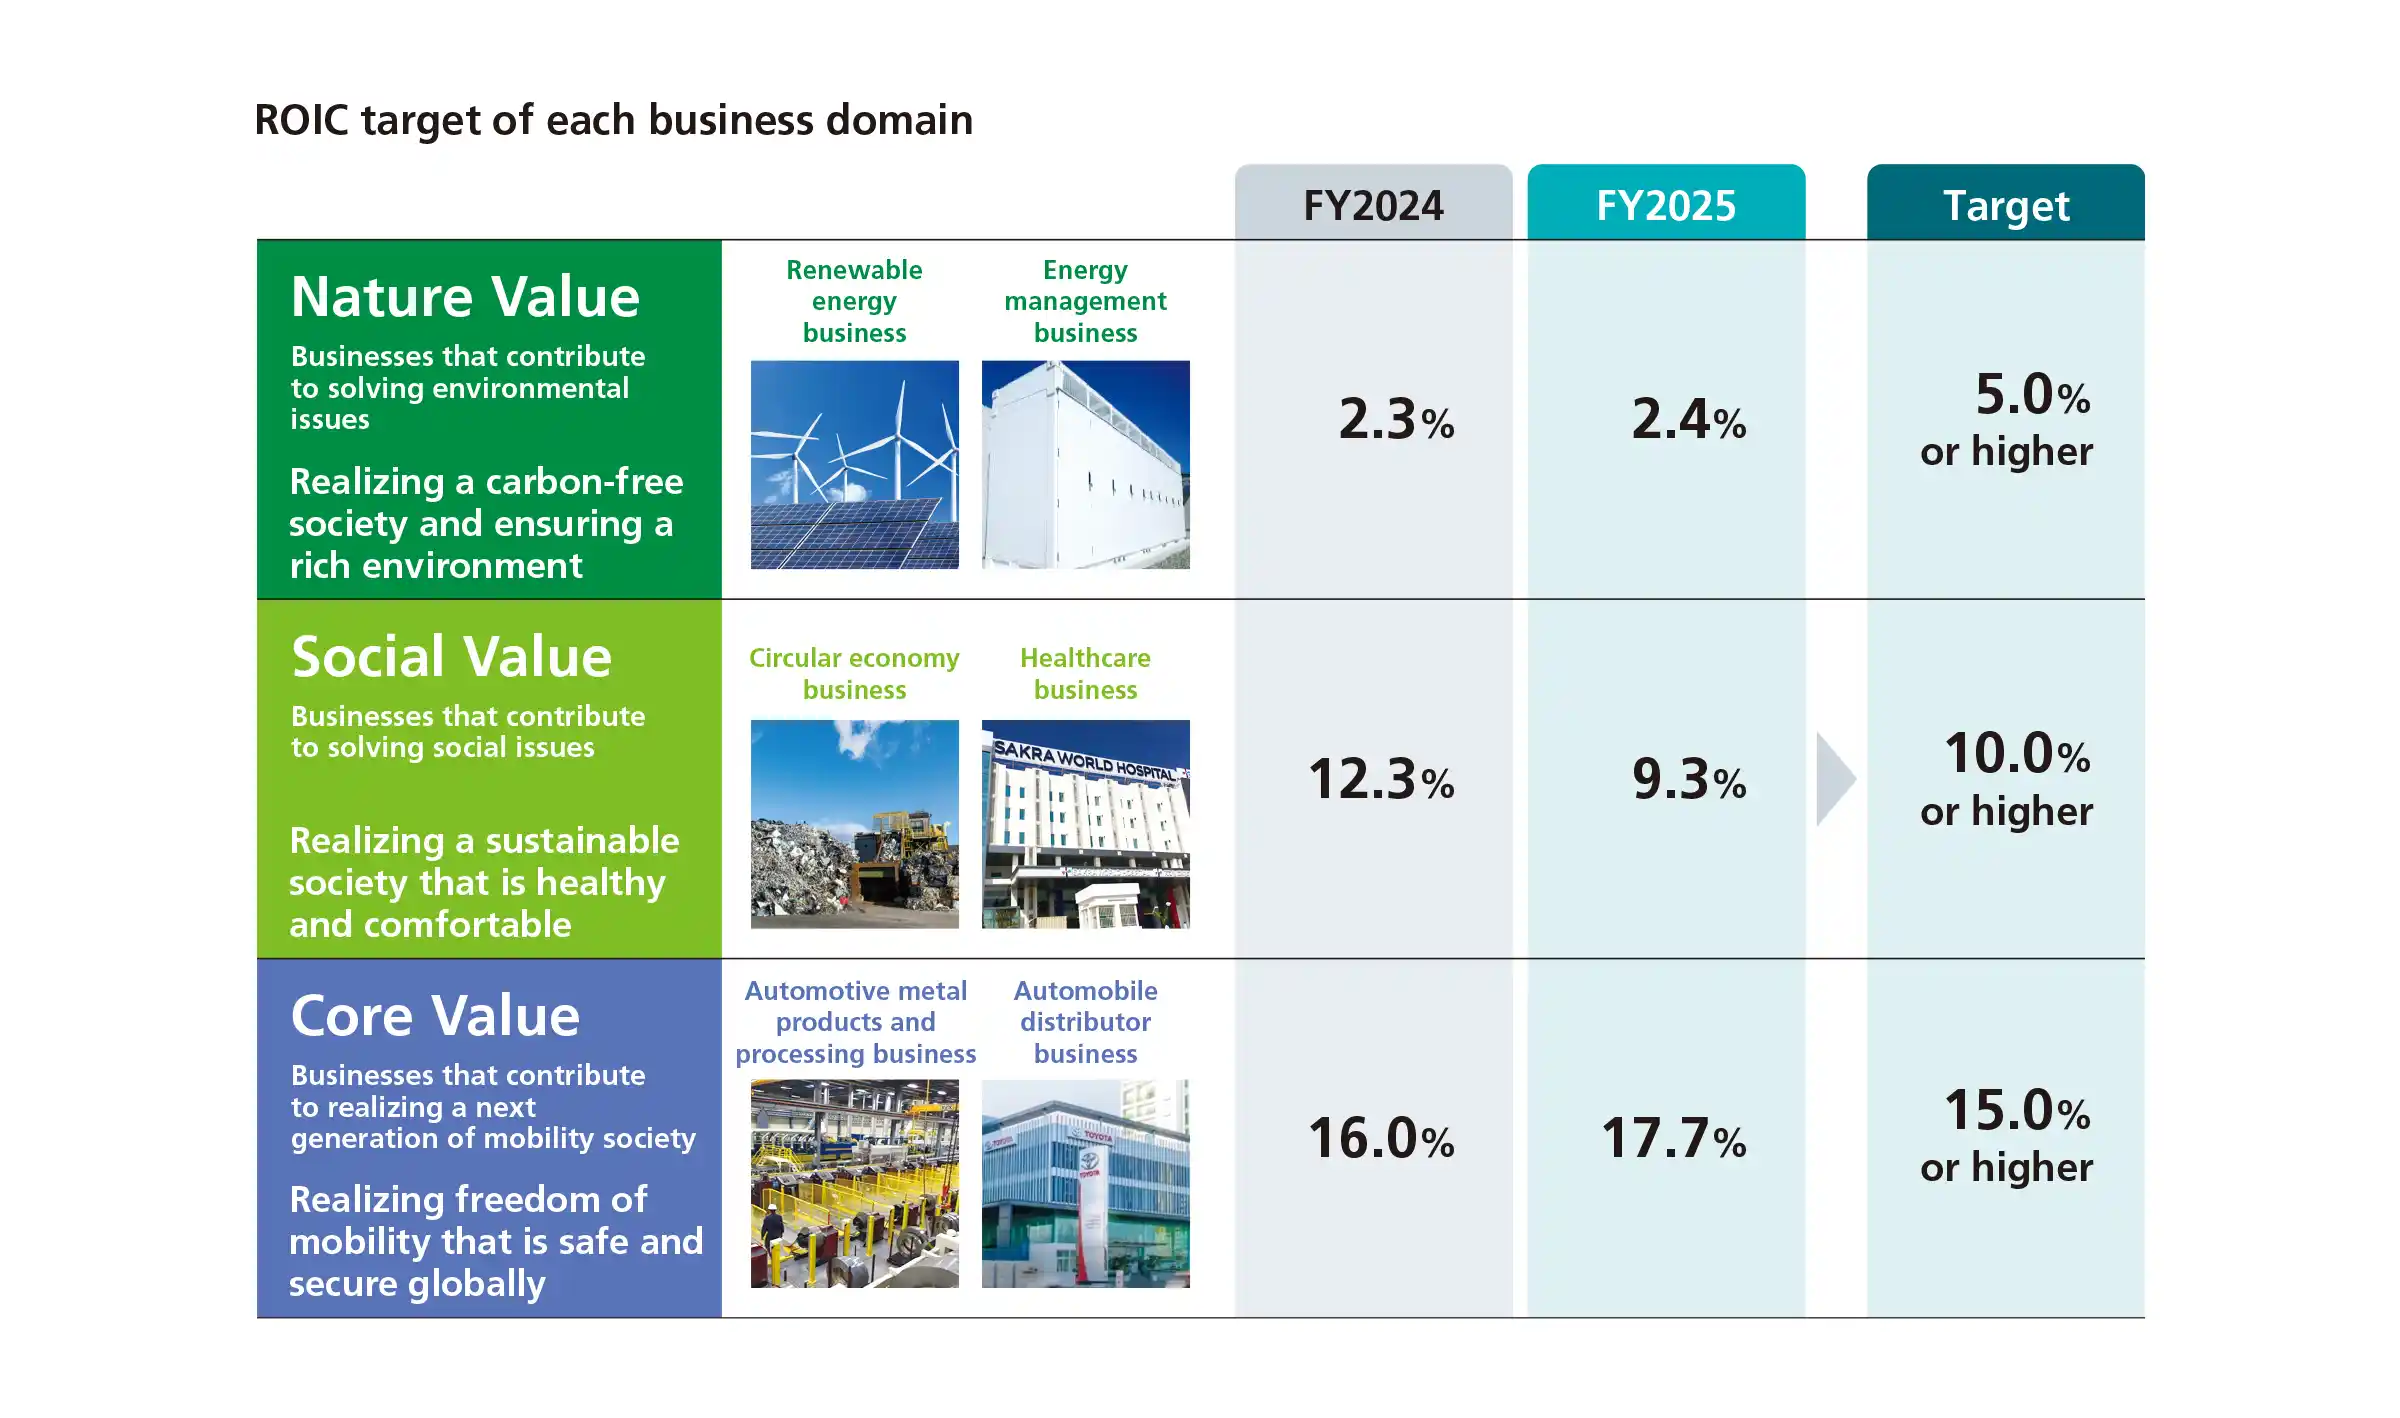
Optimizing Capital Allocation with an Emphasis on Financial Discipline
In addition to pursuing returns, we are also working to improve capital efficiency to achieve this target.
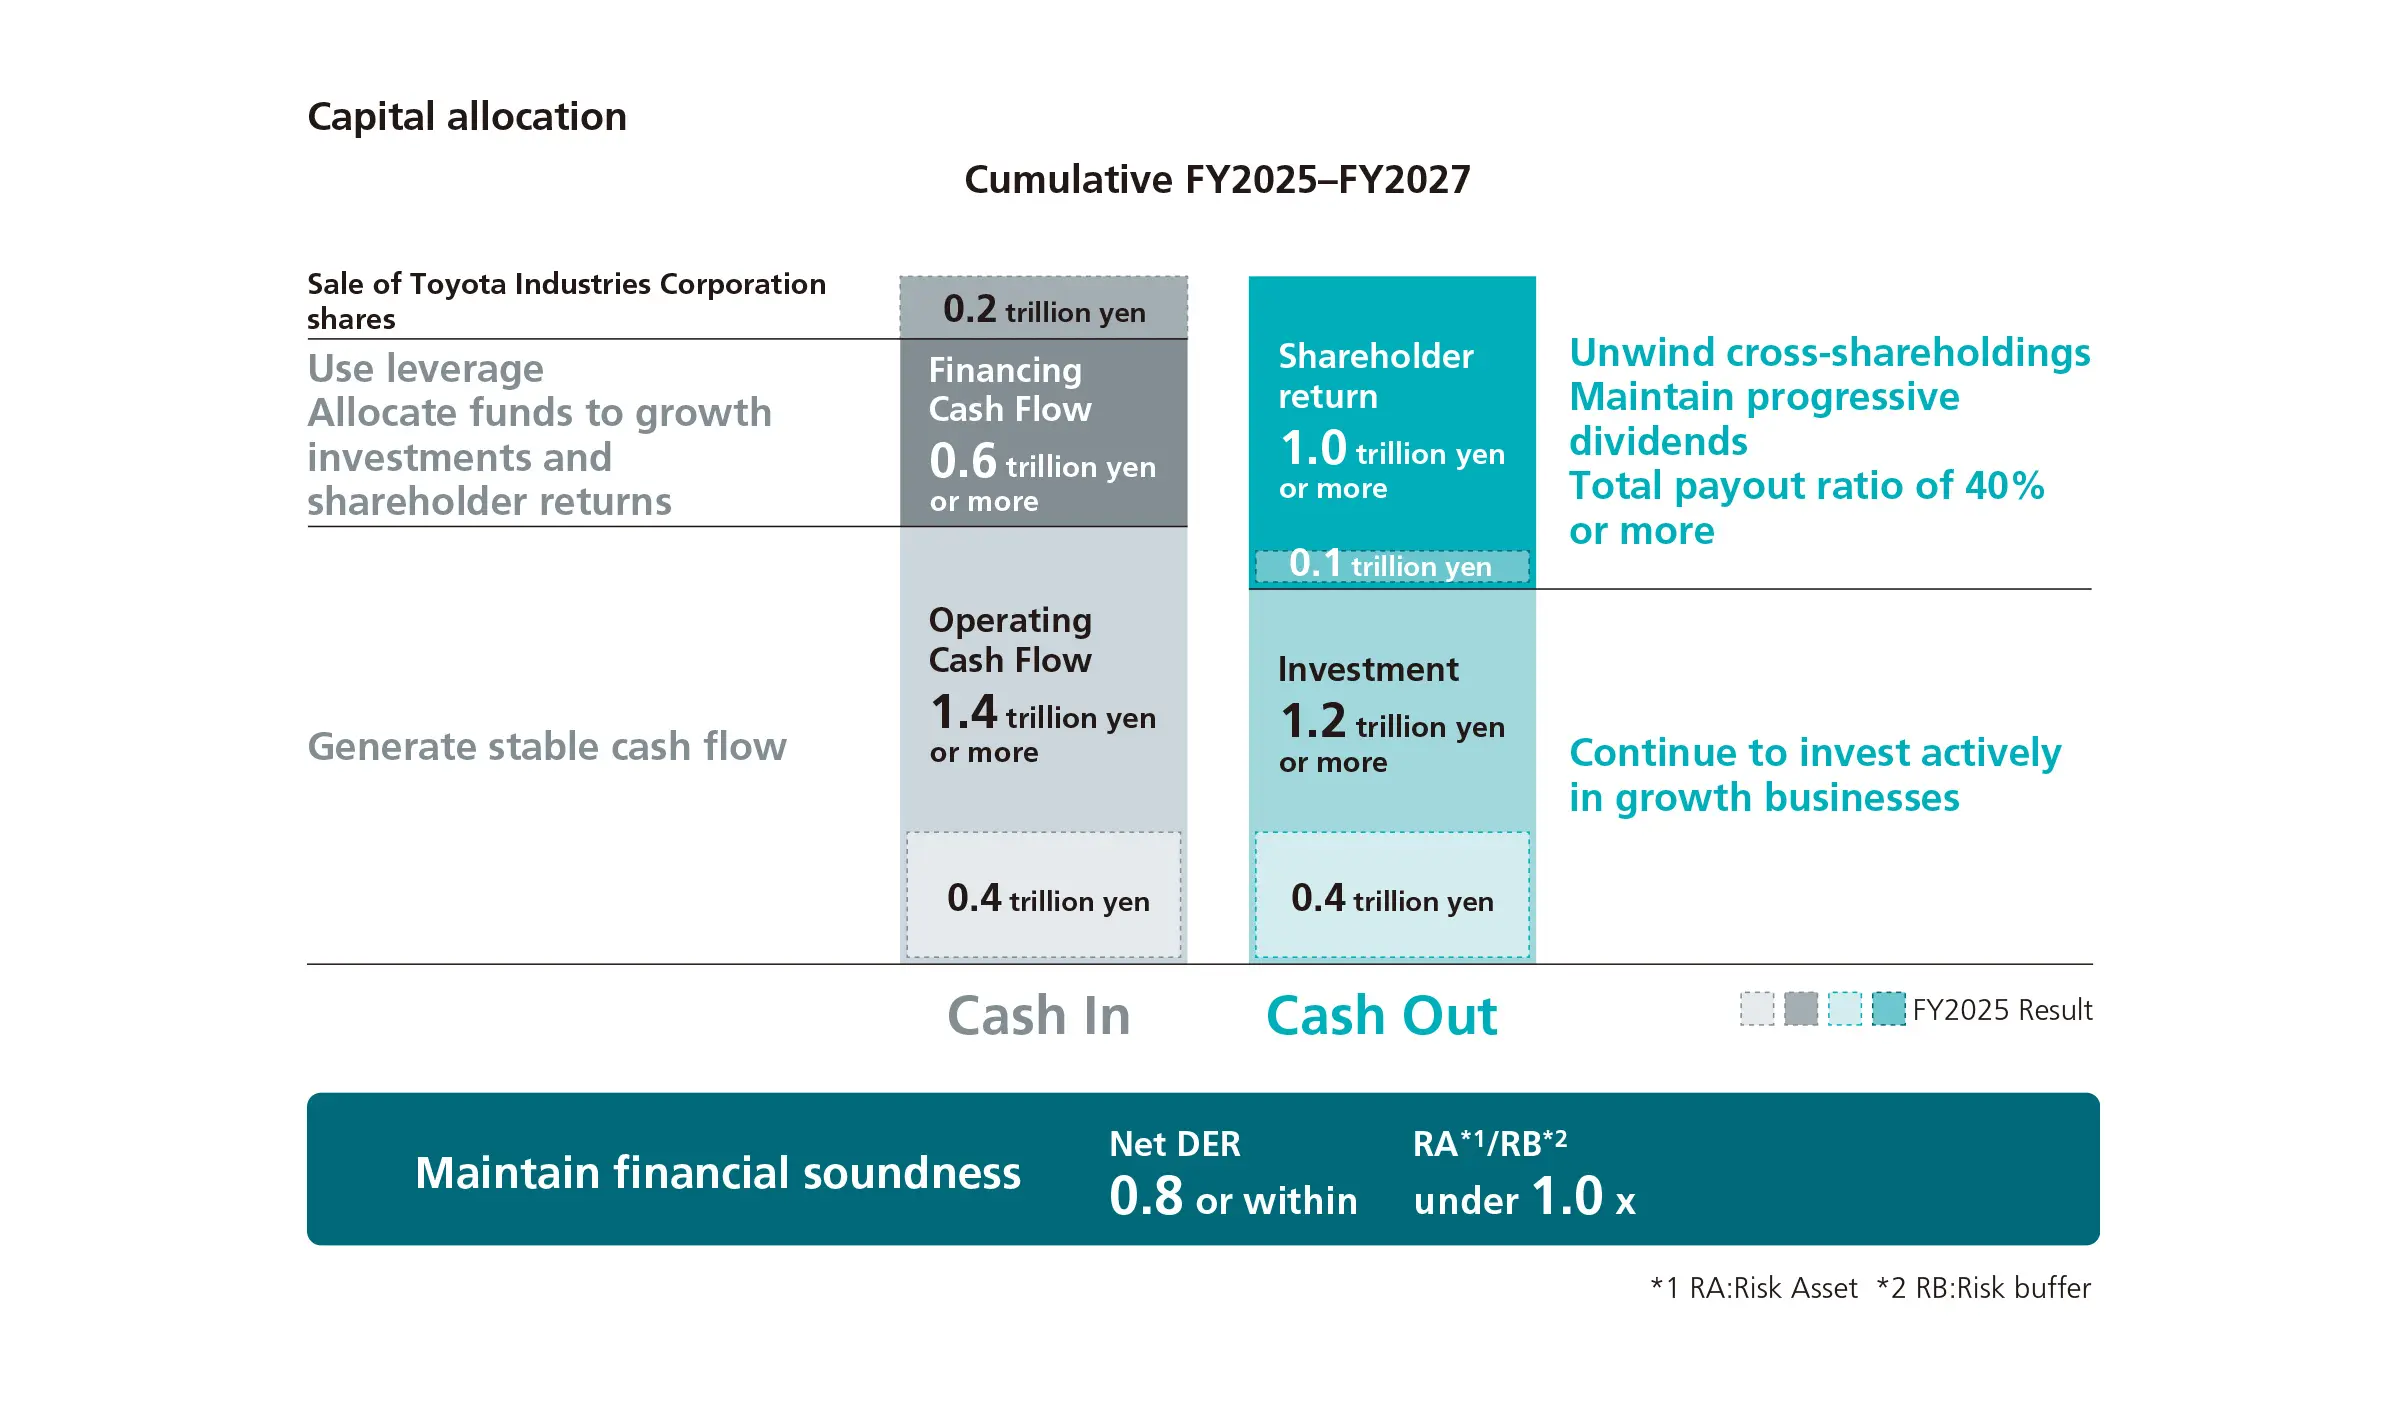
In terms of pursuing returns, we will actively invest at an even higher rate than before. In the MTP, we anticipate a three-year cumulative operating cash flow of 1.4 trillion yen, and we believe we can steadily generate roughly 500.0 billion yen in cash annually. Backed by this cash generation power, we will steadily build up the capital we will use in growth investments.
A strong focus on financial discipline lies at the foundation of our management. We maintain our net DER indicator of up to 0.8 times, and we maintain sufficient financial capacity to actively handle future large-scale investments and M&As. We believe that while maintaining this discipline, we can proceed with a total of 1.2 trillion yen in investment during the MTP period while achieving an ROE of 15%.
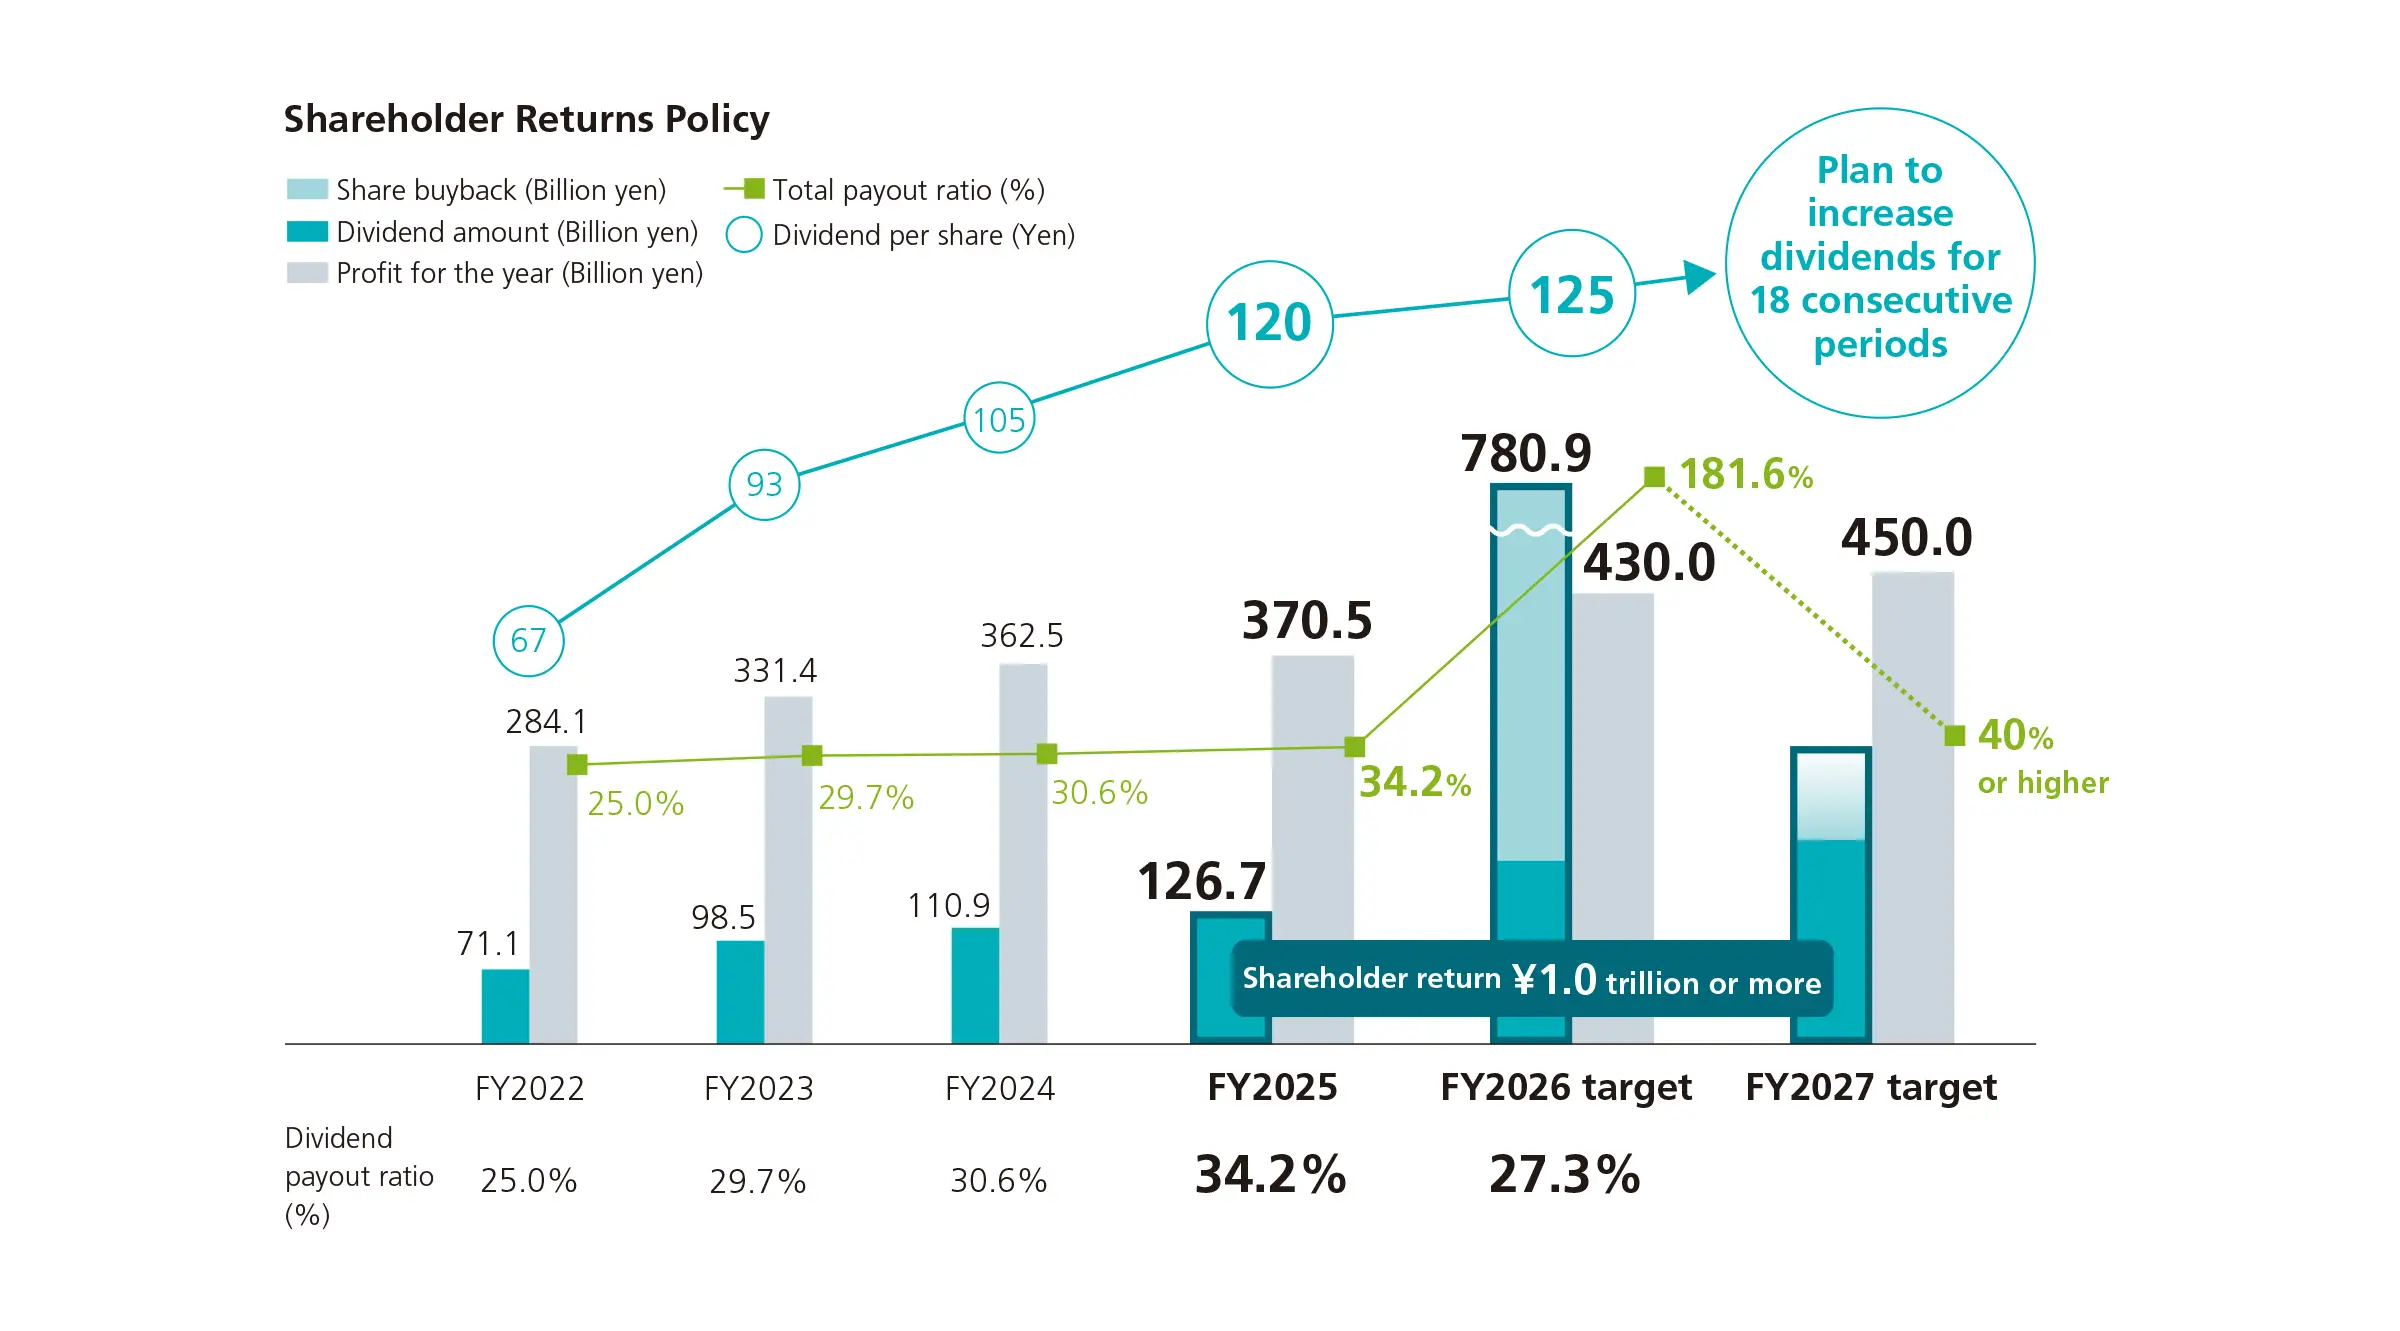
For our shareholder returns, We will continue to provide steady returns through progressive dividends. We continued to provide stable shareholder returns through progressive dividends and, with funds generated through measures such as share sales, completed a 663.6 billion yen share repurchase by the end of June 2026. With respect to the acquisition of treasury stocks, we prioritized this below growth investment in the past, but it is positioned as an important method for achieving an ROE of 15%, so we will continue to acquire treasury stock while keeping a close eye on the balance of treasury stock acquisition and growth investment.
We will also continuously review and revise our strategic cross-shareholdings.
In the fiscal year ending March 31, 2026, we eliminated cross-shareholdings with Toyota Industries Corporation, which accounted for a large portion of our strategic cross-shareholdings, bringing our strategic cross-shareholdings ratio down significantly.
I see this as an important step toward improving our capital efficiency. We will continue confirming the validity of our holdings from the perspectives not only of their significance to our business strategies and their contributions to our trading relationships, but also of whether they generate value that surpasses capital costs.
We won’t maintain financial discipline through these initiatives simply by matching up the numbers. We will also create a foundation of business and assets that we can control, and we will accurately assess the current state of our management operations and build a financial base that enables dynamic decision-making.
Using Dialog to Provide a Deeper Understanding of Our Corporate Value
These changes in how our company is evaluated have been reflected in our rising stock prices, but it is also vital that we continuously produce results that meet those expectations.
We are now making steady progress toward realizing the goals of the MTP. We will be entering the final phase of completion, and the president & CEO and all of our management team will work to achieve our targets, driven by our strong commitment. We hope that our shareholders and investors will continue to have high hopes for our growth, and we appreciate their support.